One of the questions I get most often from buyers is some version of this: “Should I buy in Kona town or out at one of the resorts?” It’s a great question, and the honest answer is — it depends entirely on how you plan to live here.
I’ve worked with buyers on both sides of this decision, and both can be the right call. What matters is being clear on your priorities before you start writing offers.
Buying in Kailua-Kona puts you close to everyday life — coffee shops, grocery runs, the farmers market on Saturday mornings, and Alii Drive for evening walks. You’re also about 20 minutes from the airport, which makes a big difference when you’re flying in and out regularly or hosting family.
Entry prices tend to be lower than the resort corridor. You can find 1-bedroom units in the low-to-mid $400Ks, with larger or oceanfront units running up toward $800K–$1.2M. HOA fees are typically in the $700–$900/month range. Financing is often more straightforward too — many Kona town condos qualify for conventional loans, which widens your buyer pool when it’s time to sell.
If you’re planning to rent, Kona condos draw a steady stream of travelers who want to be close to town. That often translates to more consistent year-round occupancy, even if the nightly rates are lower than at a full resort.
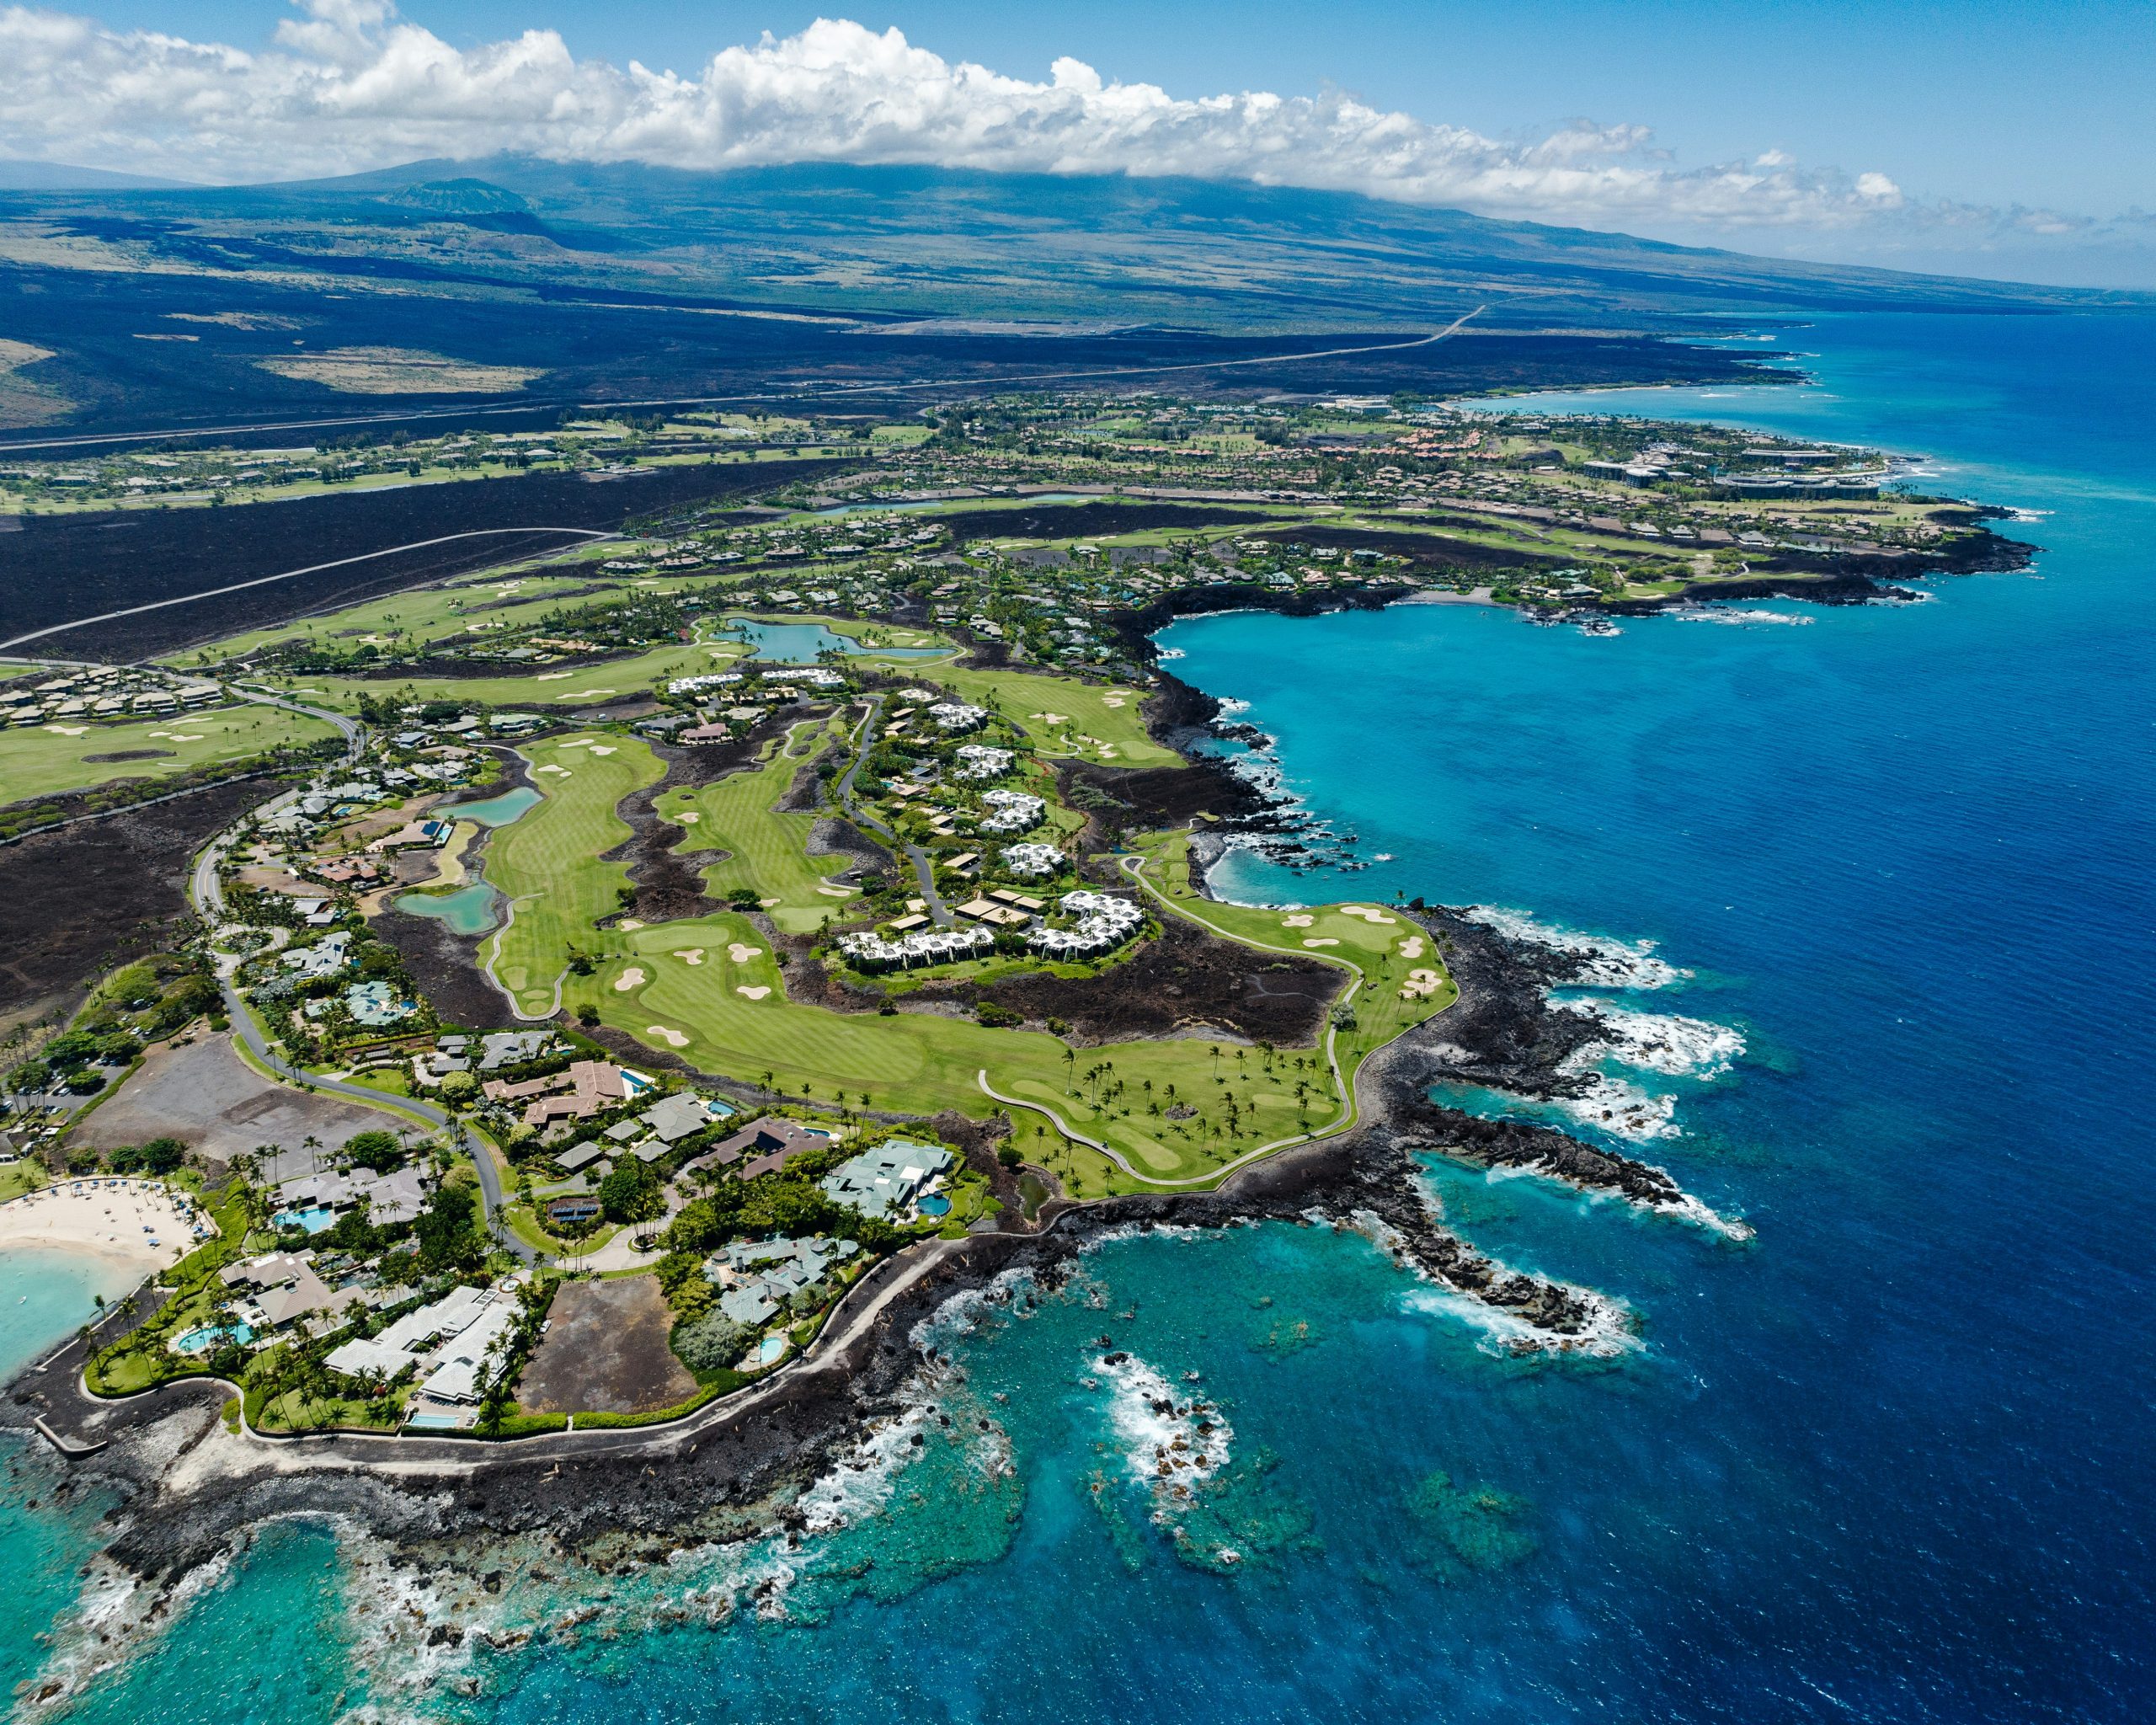
The resort corridor — Waikoloa, Mauna Lani, Mauna Kea — is a different world. You’re buying into a lifestyle: pools, beach clubs, golf, spa, dining, and all of it steps from your front door. Most people who go this route aren’t looking for walkable errands. They want the feeling of being on vacation every single day.
That experience comes at a price. Expect to start around $800K for a modest 2-bedroom, with larger or view units ranging well into the $1–2M+ territory. HOA fees reflect the amenities — often $1,000/month or more. And because many resort projects operate like hotels, financing can be more complex. Some are considered “condotels” by lenders and may require portfolio loans with higher down payments. This is something to sort out early in the process.
On the rental side, resort condos can command higher nightly rates, especially in peak season. But operating costs are also higher, so model your net yield carefully — management fees, HOA, taxes, and turnovers add up.
Whichever direction you go, Hawaii’s rental tax structure is something every buyer needs to understand before they underwrite income. You’re looking at State Transient Accommodations Tax, County TAT, and General Excise Tax — all of which come out of your gross rental revenue. The state TAT was also recently increased under Act 96 (effective 2026), so make sure your numbers reflect current rates, not older estimates.
Hawaii County also has a registration system for short-term vacation rentals that’s been tightened in recent years. And even where zoning allows rentals, your condo’s governing documents may restrict them or require a minimum stay. Always verify before you assume.
If you value everyday convenience, a lower entry price, and simpler financing — Kona town is probably your fit. If you want a turnkey resort lifestyle with beach, golf, and dining outside your door — the Kohala Coast delivers that, with the understanding that your carrying costs will be higher.
I’m happy to put together a side-by-side comparison for any specific buildings you’re considering. Reach out and let’s talk through it.
Every move starts with a conversation. Whether you’re just exploring or ready to make a move, I’m here to help.